
How Construction Mortgage Draw Schedules Work in Toronto
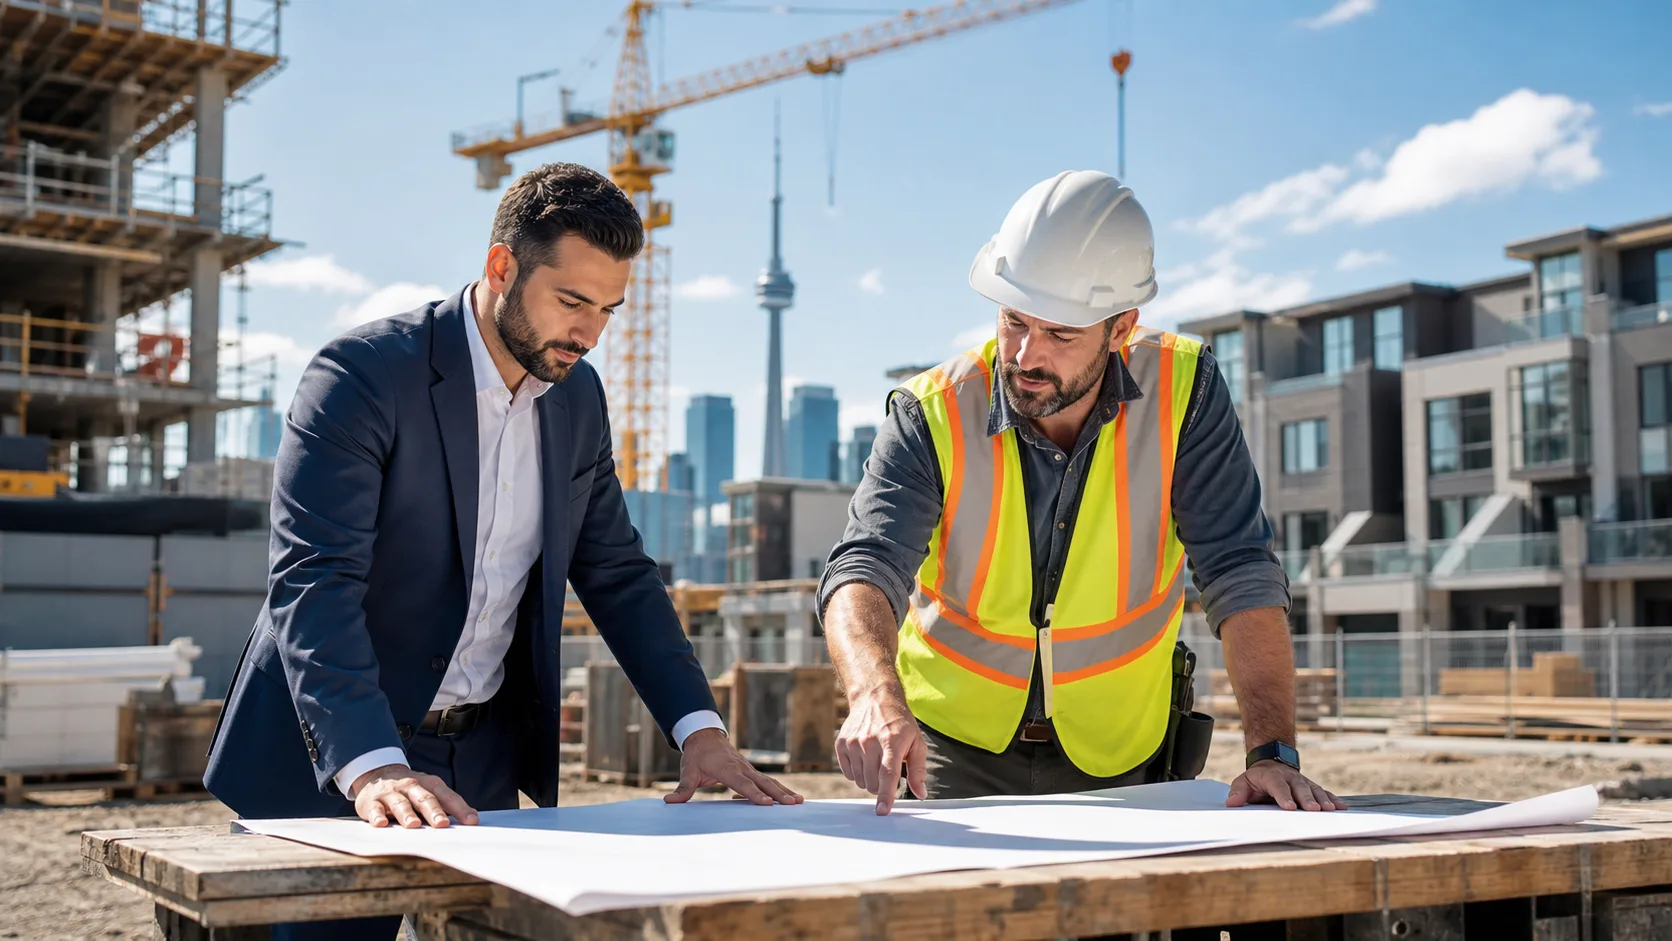
A construction mortgage in Toronto usually does not provide all your financing on closing day. Instead, the lender releases funds in stages as your build reaches approved milestones. A clear draw schedule helps you plan for contractor payments, material orders, inspections, and the timing of your own contributions.
Unlike a standard mortgage for a completed home, construction financing is tied to work that still needs to be done. In Toronto, permit timelines, labour availability, weather, and delivery delays can all affect when a project reaches its next stage. At CA Mortgage Group, we compare construction, commercial, alternative, and private financing options from more than 200 lenders to help match the structure to your project, income, credit, and available equity.
How a Construction Mortgage in Toronto Funds Your Build
With a construction mortgage, the lender approves a total mortgage commitment but advances the money gradually. Each release of money is called a draw. Before a draw is issued, the lender generally needs confirmation that the agreed stage of work has been completed.
The exact schedule depends on the lender, the property, the builder contract, and whether you already own the land. A custom home, infill project, major renovation, or small multi-unit build may all be structured differently.
A typical draw schedule may include stages such as:
- Land closing or an initial advance, if the land is being purchased as part of the project
- Foundation completion, after excavation and concrete work are finished
- Framing and enclosure, once the structure, roof, windows, and exterior protection are in place
- Interior finishing, including mechanical work, drywall, cabinetry, and other approved progress
- Final completion or occupancy, when the project meets the lender’s final requirements
Some lenders treat land equity as part of your contribution. Others may require you to use personal funds for early work before their first draw is released. We review those details closely because the timing can affect whether your builder has enough cash flow to keep work moving.
Interest is often charged on the money that has been advanced, rather than the full approved mortgage amount. During construction, you may make interest-only payments until the project is complete and the mortgage converts into a longer-term mortgage. Terms vary, so it is important that the repayment plan fits the construction period, not just the completed property.
What Lenders Review Before Releasing a Draw
Lenders need a full picture of the build before approving construction financing. That usually starts with documents showing what will be built, who will build it, how long it should take, and how the budget is expected to work.
We often help borrowers prepare for requests such as:
- Construction plans, municipal permits, and a detailed scope of work
- A builder contract, timeline, and itemized budget
- An appraisal based on the property’s expected value once completed
- Proof of land ownership or details of the land purchase
- Evidence of available funds for required equity, soft costs, and contingencies
Before the next draw, the lender or an approved appraiser may inspect the site. The inspection confirms that the claimed stage is complete and that the work supports the amount being requested. This process can feel slow when trades are waiting to be paid, but it helps prevent too much money from being advanced before the property supports it.
Draws may be delayed when work is incomplete, invoices are missing, permits have expired, or the project has changed from the original plans. Contractor disputes, lien concerns, budget gaps, and insufficient borrower contributions can also create problems. We recommend keeping invoices, receipts, change orders, inspection records, and builder communications organized from the start. Good records make it easier to explain progress and respond quickly when the lender has questions.
Build a Draw Schedule That Protects Your Budget
A strong schedule accounts for the fact that lender money may arrive after work is completed, not before. Your contractor may expect payment at specific points, while the lender may need time to order an inspection, review the report, and process the draw. If those timelines do not line up, the project can pause even when the overall mortgage approval looks adequate.
Your own funds may be needed before construction draws begin. Depending on the loan structure, that could include your down payment, land equity, architectural work, permit fees, early site preparation, demolition, or other pre-construction expenses. We help you look beyond the total mortgage amount and focus on when each dollar is needed.
A realistic budget should also leave room for surprises. Labour changes, material availability, utility connections, site conditions, inspections, interest payments, and schedule extensions can affect the amount of cash needed during the build. A contingency reserve gives you more room to respond without interrupting the work.
Before signing a builder agreement, make sure you understand whether the lender reimburses completed work or can advance funds based on an approved progress report. Clarify who requests inspections, how long the process may take, and what paperwork is required for each draw. Small timing gaps can turn into contractor delays and added carrying expenses if they are not planned for early.
Winter Planning for Construction Financing
Late autumn and winter can add another layer of planning to a construction mortgage in Toronto. Cold temperatures, snow, and limited site access may affect excavation, concrete work, roofing, exterior finishes, and deliveries. A project that is not enclosed before severe weather arrives may take longer to reach its next draw milestone.
Municipal inspection availability and lender processing timelines may also be tighter around year-end. We encourage you to ask how weather-related delays will be handled before committing to major material orders or signing a construction contract. A schedule should allow room for conditions that are outside your builder’s control.
Some projects do not fit standard bank guidelines, especially when timing is tight, income is non-traditional, credit has changed, or land equity is doing much of the work. In those situations, we can compare options that may include alternative construction financing, private mortgages, second mortgages, refinance strategies, land equity solutions, and bridge financing. The right option depends on the full project plan and a clear exit strategy once construction is complete.
Plan Your Construction Financing Before Work Begins
Construction financing should support the full build timeline, from land and permits through final occupancy and long-term mortgage planning. The highest approval amount is not always the best fit if draw timing, borrower contributions, inspections, or repayment terms create pressure during construction.
Before buying land, starting demolition, signing a construction agreement, or requesting the first draw, take time to confirm the schedule, documents, contingency funds, and lender conditions. Careful planning gives you a better chance of keeping trades paid, work progressing, and financing aligned with the project from start to finish.
Find Financing That Fits Your Build
CA Mortgage Group can help you compare lender options and structure a construction mortgage in Toronto around your project’s requirements. With access to more than 200 lenders, we assess solutions beyond a single institution’s offerings. Contact us to discuss your plans and financing needs with our team.